Investment in quick commerce remains strong, but rising competition is pushing companies to focus on turning rapid growth and scale into sustainable profits.
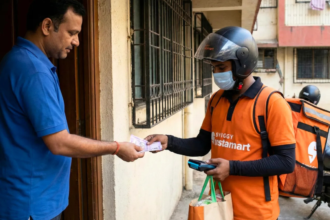
India’s quick-commerce sector is entering a new phase. After years of competing on delivery times, dark-store expansion, and customer acquisition, the industry is now facing a harder question: how much of that scale can actually generate sustainable profits?
Investment remains strong, but the economics are becoming more important than ever. As of Q1FY27, Blinkit was the only major quick-commerce player to report positive EBITDA, with an adjusted EBITDA margin of 0.6% and EBITDA of roughly Rs 3 per order.
Instamart, despite improving its economics, was still losing around Rs 68 per order, while Zepto’s EBITDA loss was nearly Rs 60 per order in Q4FY26. Swiggy said Instamart improved adjusted EBITDA per order by Rs 29 over the past year.
The figures highlight a shift in how the industry is being assessed. Order volumes, GMV and dark-store counts can show growth, but the more important question is what remains after the cost of fulfilling every order.
Competition Is Getting More Intense
Quick commerce is no longer a three-player race.
Amazon is stepping up its India investment, with plans to invest $48 billion through 2030, while Flipkart is expanding its Minutes business. Both companies are bringing large customer bases, technology, supply chains and capital into a market once dominated by Blinkit, Instamart and Zepto.
The established players are also making changes.
Zepto has put its IPO plans on hold amid questions around valuation and profitability. Swiggy has reshuffled Instamart’s leadership, while BigBasket has appointed a new CEO as Tata Group’s digital businesses undergo a broader transition.
Blinkit, meanwhile, is shifting its focus from simply adding dark stores to improving productivity across its existing network. The company reported revenue of around Rs 38,000 crore in FY26 and has become the first major player to demonstrate positive EBITDA at scale.
Discounts Are Easing, But Profits Are Still Difficult
The industry’s early growth depended heavily on discounts, free deliveries and aggressive customer acquisition.
UBS research shows discounts have stabilised at around 19-20% over the past three to four months, compared with 24-27% between October 2025 and March 2026.
Lower discounts can improve economics, but they do not automatically make a business profitable.
BigBasket’s FY26 numbers illustrate the challenge. The company spent roughly Rs 1.37 to generate every Rs 1 of revenue, translating into a loss of around Rs 37 for every Rs 100 of revenue generated.
For a business built around low-margin grocery, the cost structure remains difficult.
A typical dark store needs around 1,100-1,200 orders a day to break even, although the threshold varies depending on location and real estate costs.
Apoorve Goyal, Managing Director, India Investments at Prosus, said profitability depends on more than average order value. Operational efficiency, pricing power, store productivity and delivery performance all contribute to the bottom line.
Blinkit is believed to command a premium even on identical products, with experts estimating prices around 15% above offline retail, 10% above Instamart and 5% above Zepto.
That pricing power can improve margins while also supporting expansion into adjacent categories.
The Market Is Still Far From Saturated
The reset is happening even as the potential market continues to expand.
Navin Killa, Head of Asian Telecoms, Media, and Internet Research at UBS Global Research, said the quick-commerce opportunity was initially viewed as a $15-20 billion market when the sector began accelerating in 2021.
The opportunity has since expanded considerably as platforms moved beyond groceries and demonstrated that consumers were willing to buy a much wider range of products through fast delivery.
Google and Deloitte estimate that India’s quick-commerce market could reach $250 billion by 2030, compared with an estimated $50 billion as of April this year.
India’s online grocery market, meanwhile, was worth around $12 billion in 2025, according to Ken Research, and is projected to reach $103 billion by 2030. Online grocery still represents only 1-2% of urban grocery consumption.
That leaves substantial room for growth. The challenge is whether the economics of today’s dense urban networks can be replicated across a much larger market.
Six Players, Six Different Strategies
The leading companies are entering the next phase from very different positions.
Instamart is trying to regain market share after losing ground to Zepto while improving its unit economics. Satish Meena, founder of Datum Intelligence, said the business now faces the challenge of balancing growth with profitability.
Zepto continues to target value-conscious consumers while scaling its network, but its decision to put its IPO on hold has brought greater attention to its profitability and valuation.
Flipkart Minutes is relying on the wider Flipkart ecosystem. Kunal Gupta, Senior Vice President and Head of Flipkart Minutes Business, said the platform has scaled to 1,000 micro-fulfilment centres across more than 130 cities and 8,000-plus pincodes, with order volumes growing fivefold over the past year.
Amazon Now has the backing of Amazon’s wider ecosystem and financial resources, although it still needs to build customer habits in a market where consumers are already accustomed to incumbent platforms.
BigBasket faces a different challenge. Once a major force in online grocery, it now has to reposition itself within a quick-commerce market that has changed the economics of the category.
JioMart is also participating in the race, although its position in quick commerce remains less clearly defined.
According to Badri Narayanan Gopalakrishnan, founder of Infisum, Blinkit, Instamart and Zepto together account for around 90% of the quick-commerce market, leaving the remaining players to compete for the balance.
Grocery Alone Cannot Deliver the Margins.
Grocery remains the foundation of quick commerce, but it is also a low-margin category.
Redseer estimates that grocery accounts for 71% of quick-commerce GMV, while non-grocery categories contribute the remaining 29%. Beauty and personal care alone account for more than 8%.
That is pushing platforms towards categories that can support larger baskets and better margins.
Private labels are becoming an important part of that strategy. Instamart has developed brands such as Supreme Harvest and Nectr, while Swiggy’s Noice spans products including paneer, bread, ice creams and smoothies. Blinkit has Whole Farm, while Zepto operates Daily Good.
Private labels can give platforms greater control over pricing and margins while creating products that consumers may specifically seek out.
Apoorve Goyal said private labels can also support customer retention. If consumers visit a platform for a particular private-label product, they may buy the rest of their basket there as well.
For FMCG companies, however, the growing presence of private labels creates a more complicated relationship with quick-commerce platforms. Platforms need established brands for assortment and advertising revenue, while simultaneously building products that compete with them.
The Next Battle Is Outside the Metros
The industry’s next major test will be expansion beyond India’s largest cities.
A Deloitte-FICCI report says Tier-II and Tier-III cities now account for more than 60% of India’s e-commerce transactions. Deloitte expects Tier-II cities to account for 30% of quick-commerce spending by 2030.
Flipkart says its Tier-II and Tier-III business has grown 42 times over the past year as it expanded into more than 90 new cities.
But smaller cities present a different economic equation. A dark store may need to serve a much larger geographic area, while delivery promises could shift from 10-15 minutes towards 30 minutes.
The challenge is determining whether a market can support several competing networks.
Blinkit operates in 300 cities with more than 2,400 dark stores. Instamart operates in 128 cities with 1,181 dark stores, while Zepto operates in 61 cities with 1,225 dark stores. Flipkart Minutes says it is on track to reach around 1,500 micro-fulfilment centres across more than 150 cities.
The expansion shows how much capital is still flowing into the sector. It also raises the question of whether all these networks can achieve sufficient density and order volumes to become profitable.
The New Quick-Commerce Equation
Quick commerce is not slowing down. It is changing.
The first phase was about proving that consumers would pay for convenience measured in minutes. The next phase is about proving that the convenience can support profitable businesses.
That will require higher order density, tighter operations, stronger pricing, better use of dark stores and greater contribution from non-grocery categories and private labels.
It will also require companies to expand without simply replicating the capital-intensive model that worked in India’s largest cities.
The companies that emerge strongest from this reset may not be those with the most dark stores or the fastest delivery promises. The more important measure will be whether they can turn network density into productivity, frequent grocery orders into higher-margin baskets, and rapid growth into sustainable cash generation.
Read more news and follow us on Instagram.
Source: BT